Business Loans in Australia: What Lenders Actually Look At (A Guide for Brisbane Business Owners)
Published by Lifte Loans | Author: Jolly Dua, Credit Representative 531734, National Mortgage Brokers (ACL 391209)
If you’ve applied for a business loan before and felt like you were being assessed on things that had nothing to do with how well your business is actually doing, you’re not imagining it. Business lending works differently to home lending, and understanding how can save Brisbane business owners a lot of frustration.
It’s rarely just about the business
A common assumption is that business loans are assessed purely on the business’s financials. In reality, especially for smaller and newer businesses, lenders often look at the business and the people behind it together. Your personal credit history, any personal guarantees involved, and your overall financial position can all factor in alongside the business numbers.
Financials need to tell a consistent story
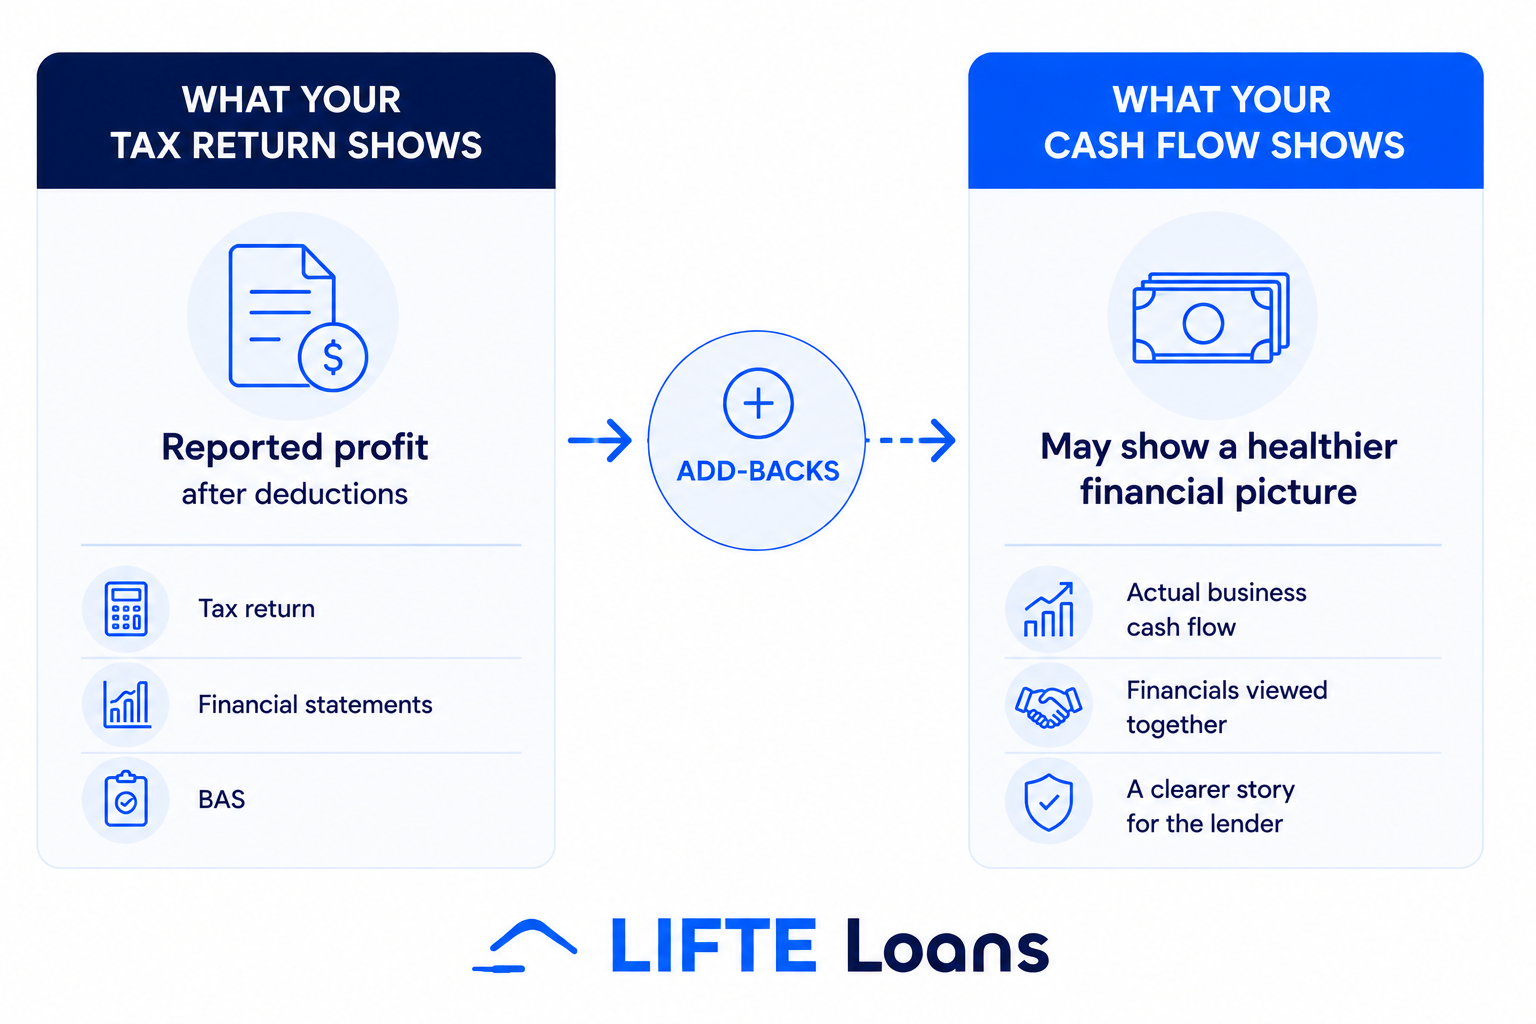
Lenders want to see financials that broadly align: tax returns, financial statements, BAS lodgements, and bank statements that tell a similar story. Say you’re in a situation like this: your tax return shows lower profit because of how your accountant has structured deductions for tax purposes, but your actual cash flow tells a healthier story. This is incredibly common, but it means add-backs and explanations matter, and having these ready, often with your accountant’s help, makes a real difference.
Security changes what’s possible
Whether the loan is secured against property, business assets, or unsecured altogether changes both what’s available and how it’s structured. Unsecured business loans exist and can be useful for shorter-term needs, but they typically come with different terms to a loan secured against a commercial property or other asset.
Purpose matters more than people think
What the funds are actually for, whether that’s equipment, working capital, expansion, or property, affects which lenders and loan types are even on the table. Being clear and specific about purpose upfront, rather than a general “business funds,” tends to lead to a smoother process.
Time in business and industry matter too
Newer businesses and certain industries are viewed differently by different lenders. This doesn’t mean a newer business can’t access finance, but the options and the lender mix might look different to an established business with several years of trading history.
Common misconceptions
“My business loan is assessed the same way as a home loan.” It generally isn’t, and that cuts both ways.
“If my tax return shows low profit, I won’t qualify.” Not necessarily, depending on add-backs and your overall cash flow story.
“Unsecured means easier to get.” Sometimes, but it usually comes with different terms, not simply “less hassle.”
How I help
Reviewing your business and personal financial position together, the way a lender will
Helping you and your accountant present financials in a way that tells a clear, consistent story
Matching loan type, security position, and lender to your specific situation
Being upfront about what’s realistic given your time in business and industry
When to reach out
If you’re exploring finance for equipment, expansion, working capital, or a commercial property, the earlier you have this conversation, the more options are usually on the table, particularly if there’s any preparation work to do with your financials first.
Exploring finance for your business?
Reach out and let’s talk through what’s realistic.
Lifte Loans 0420 604 107 | [email protected] | lifte.com.au
Jolly Dua | Credit Representative No. 531734 | National Mortgage Brokers, Australian Credit Licence 391209