Buying Property in Brisbane on a Skilled Visa: What Changes for Your Finance
Published by Lifte Loans | Author: Jolly Dua, Credit Representative 531734, National Mortgage Brokers (ACL 391209)
If you’ve moved to Brisbane or South East Queensland on a skilled visa, whether that’s a 482, 186, 494, or another employer-sponsored or skilled pathway, and you’re starting to think about buying property, you’ve probably noticed that most finance content online assumes you’re an Australian citizen or permanent resident. It isn’t written for your situation, and that gap leaves a lot of people either assuming they can’t buy yet, or not realising what’s genuinely involved.
The first thing to understand: visa status and lending policy are connected, but not in the way most people assume
Different lenders have different policies when it comes to visa holders, particularly around deposit size, loan-to-value ratios, and sometimes which visa subclasses they’ll lend to at all. This doesn’t mean it’s harder across the board, it means the lender selection matters more than it would for an Australian citizen, where most lenders are broadly similar.
Say you’re in a situation like this: you’re on a 482 visa with a strong income and a stable employer, but one lender’s policy treats your visa type more conservatively than another’s. The loan itself might be entirely realistic, it just depends on finding a lender whose policy actually fits your situation, rather than applying with whoever you happen to bank with.
What generally doesn’t change
Your income is still assessed the way anyone’s would be: stability, amount, and type all matter. Your savings history, your expenses, and your existing debts are assessed the same way too. If you’re an employed professional with a clean financial position, the fundamentals of your application aren’t dramatically different to anyone else’s.
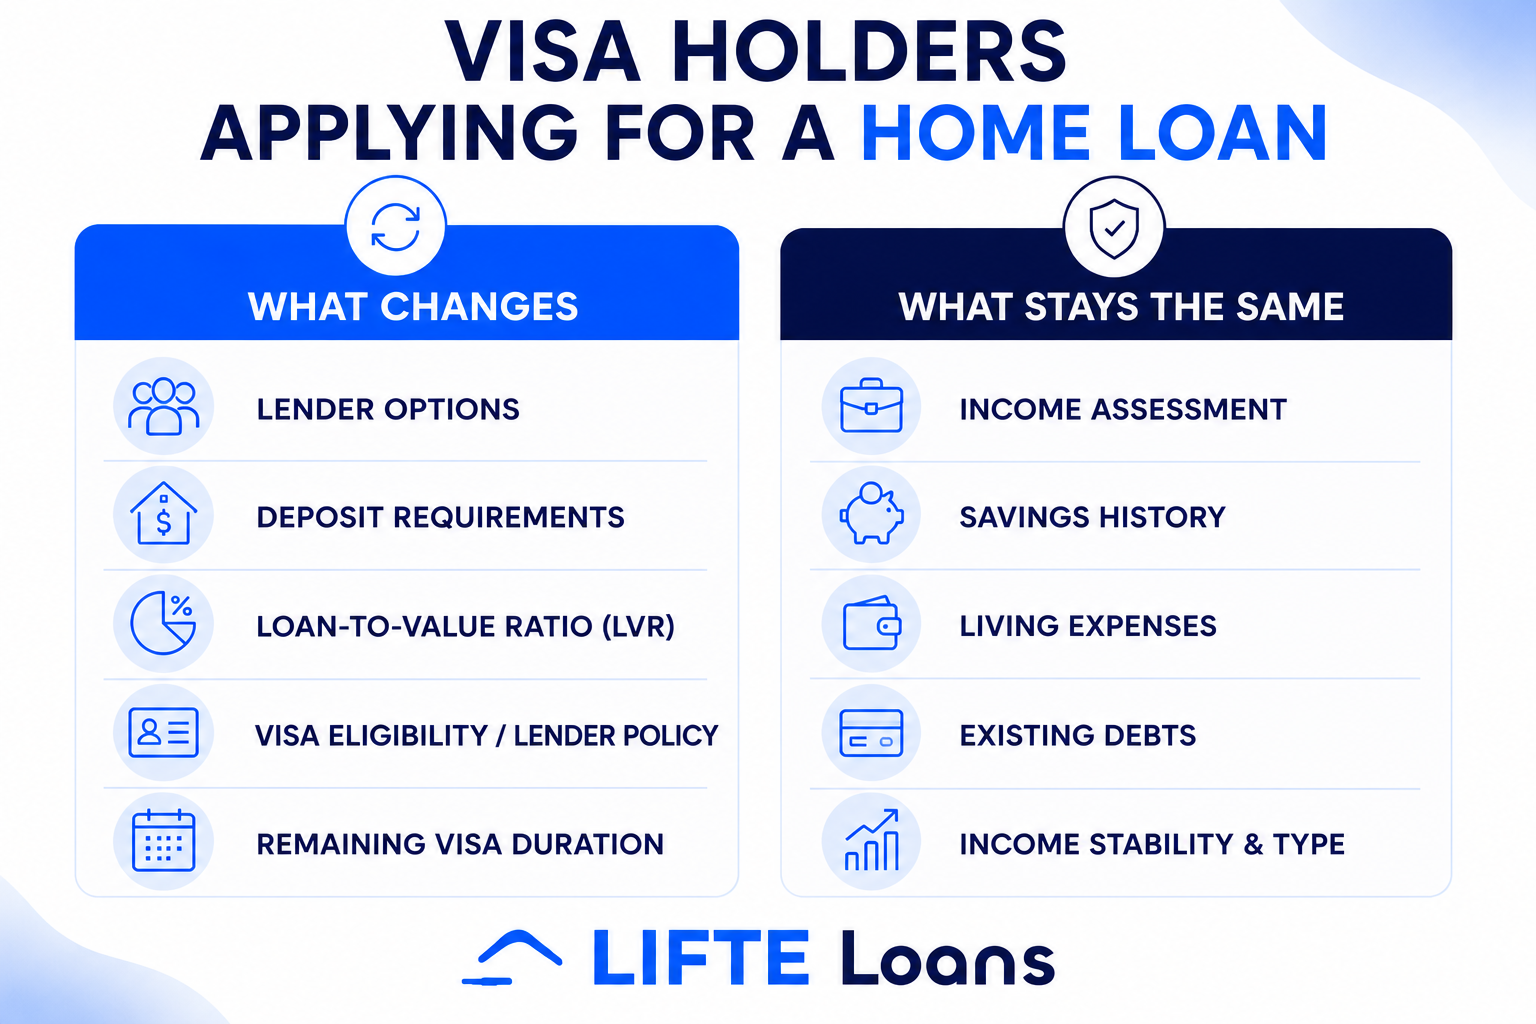
What can change
Deposit requirements can sometimes be higher for certain visa types, particularly for newer or shorter-duration visas. Some lenders may also want to see evidence of your visa’s remaining duration, or take a view on your pathway toward permanent residency. None of this is necessarily a barrier, but it’s the kind of detail that changes which lenders are worth approaching first.
Where this connects to your visa pathway
If you’re on a pathway from a temporary visa toward permanent residency (for example, from a 482 toward a 186, or from a 491 toward an 887), your timeline matters for more than just immigration purposes. It can also affect things like foreign buyer duties in Queensland and certain federal property rules, which I’ve covered in more detail in a separate post, because they genuinely deserve their own explanation rather than a passing mention here.
Common misconceptions
“I need to be a permanent resident before I can even apply.” Not true for many visa holders, though your options may differ.
“My income from overseas doesn’t count.” It can, depending on the type and how it’s documented, though it’s assessed carefully.
“Every lender treats visa holders the same way.” They don’t, and that’s exactly why lender selection matters here.
How I help
Reviewing your visa type, income, and overall position together, the way lenders will
Identifying which lenders are likely to be a genuinely good fit for your situation, rather than a generic shortlist
Being upfront about anything that might affect timing, including your visa’s remaining duration
Connecting the finance conversation with your broader visa and property timeline where relevant
When to reach out
If you’re on a skilled visa in Brisbane or South East Queensland and starting to think seriously about property, the most useful first step is an honest conversation about where you currently stand, not a generic “can I get a loan” question answered with a yes or no.
Thinking about buying property on a skilled visa?
Get in touch and let’s look at your situation properly.
Lifte Loans 0420 604 107 | [email protected] | lifte.com.au
Jolly Dua | Credit Representative No. 531734 | National Mortgage Brokers, Australian Credit Licence 391209