SMSF Property Loans Explained: What to Know Before Borrowing Through Your Super
Published by Lifte Loans | Author: Jolly Dua, Credit Representative 531734, National Mortgage Brokers (ACL 391209)
Self-managed super funds have become a popular way for Australians to take more control over their retirement savings, and for some, that includes using the fund to invest in property. If you’ve heard about SMSF loans and you’re wondering whether it’s something worth looking into, here’s what’s actually involved.
What an SMSF loan is
An SMSF loan allows a self-managed super fund to borrow money to buy an investment property, using a structure called a Limited Recourse Borrowing Arrangement, or LRBA. The “limited recourse” part means that if something goes wrong with the loan, the lender’s claim is limited to that specific property, rather than the rest of the fund’s assets.
Importantly, the property has to be a genuine investment. It can’t be lived in by you or rented to a related party, which rules out the idea of “buying your future home through your super now.”
Who tends to look into this
SMSF property loans generally suit people with an established super balance who are looking for another way to diversify their retirement savings, and who are comfortable with the extra layer of compliance involved in running an SMSF. It’s not typically a strategy for someone just starting to build up super, simply because of the balances and costs involved.
What’s required to get started
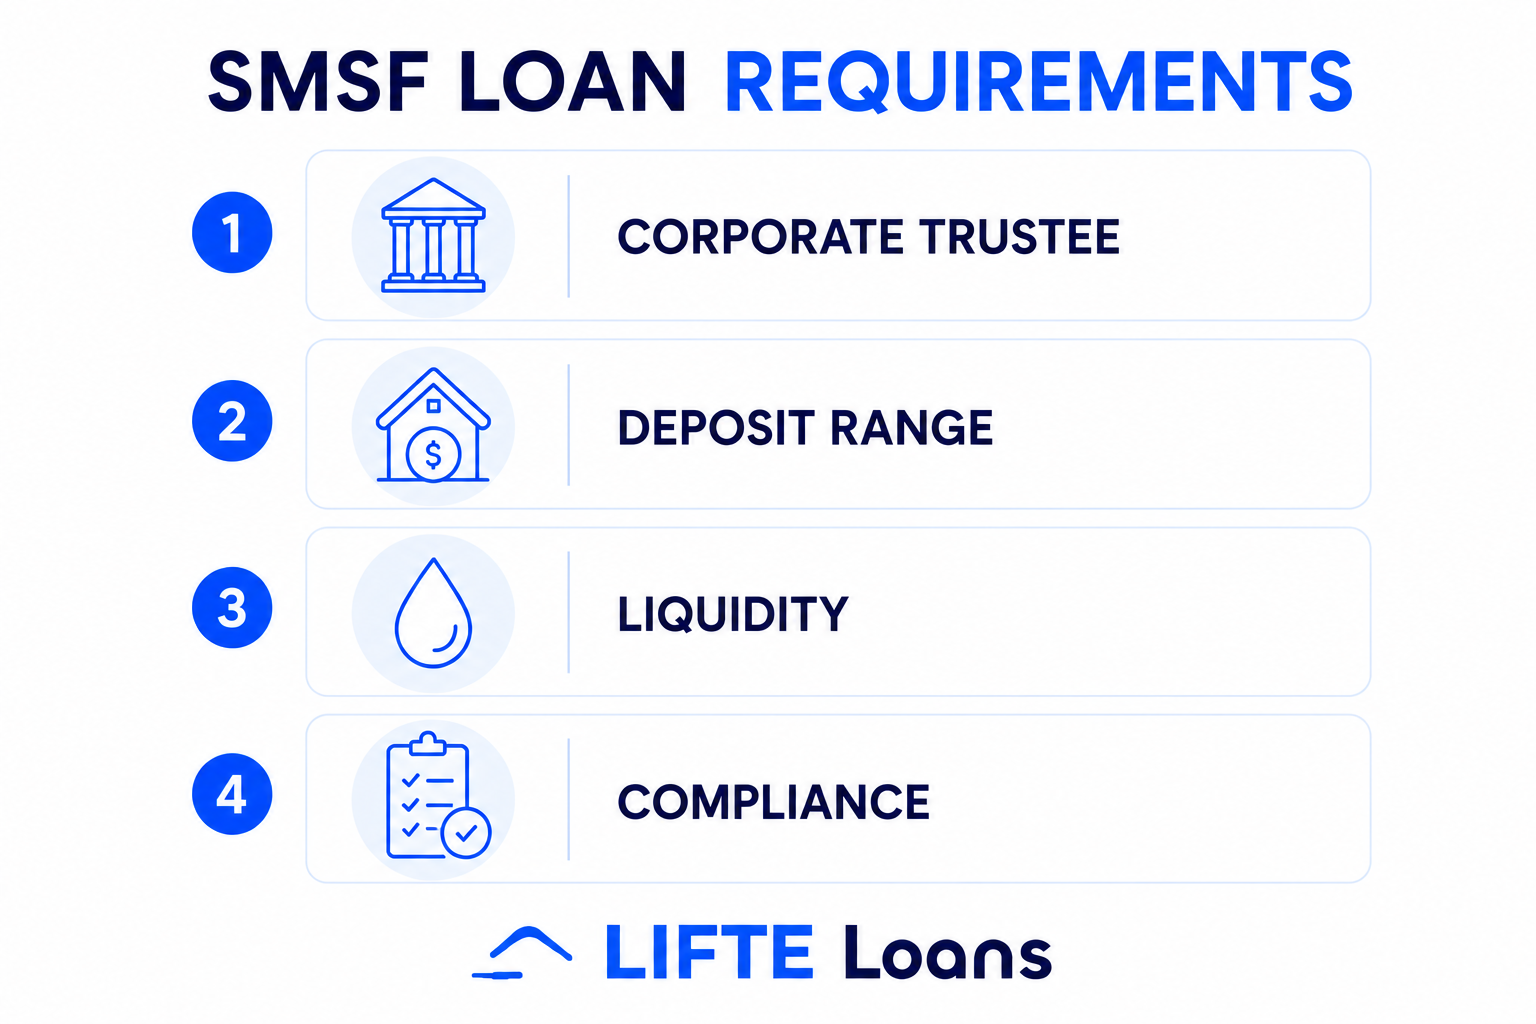
For an SMSF loan to work, the fund generally needs to be properly established and compliant, often with a corporate trustee structure, a meaningful deposit (commonly in the range of 20 to 30 percent), and enough remaining liquidity in the fund after the purchase to cover ongoing costs and obligations. The property itself also needs to fit the fund’s investment strategy and comply with superannuation rules.
What to weigh up
There’s genuinely more complexity here than with a standard investment property loan. Setup and ongoing compliance costs are higher, the pool of lenders willing to do SMSF lending is smaller, and there are restrictions around things like making improvements to the property while the loan is in place. None of this makes SMSF lending a bad option, but it’s not a decision to make casually, or without your accountant and financial adviser involved alongside the lending side.
Common misconceptions
“I can use my SMSF to buy a place I’ll live in later.” Generally not, the property needs to remain a genuine investment.
“Any SMSF can get a loan like this.” The fund needs to be properly structured and compliant first, which often takes preparation.
“This is just like any other investment property loan.” It involves more moving parts, more parties, and more compliance considerations.
How I help
Making sure the lending side of an SMSF loan is structured properly from the outset
Working alongside your accountant and financial adviser so everything lines up
Being upfront about whether your fund’s current position makes this a realistic option right now
Explaining the ongoing implications, not just the approval process
When to reach out
This is one area where I’m very upfront: an SMSF loan isn’t something I’d ever progress in isolation. If your accountant or adviser has raised this as an option, or you’re curious whether it could fit your retirement strategy, that’s the right time to bring me into the conversation alongside them.
Exploring SMSF property as part of your strategy?
Get in touch and we’ll look at how it fits with your situation.
Lifte Loans 0420 604 107 | [email protected] | lifte.com.au
Jolly Dua | Credit Representative No. 531734 | National Mortgage Brokers, Australian Credit Licence 391209